East Idaho Mortgage Calculator
Use this free East Idaho mortgage calculator to estimate your monthly payment before you shop. It adds principal, interest, taxes, insurance, PMI, and HOA fees into one clear number. That way, you can plan for homes from Rexburg and Rigby to Idaho Falls and Blackfoot.
Amount: $90,000
Payment Breakdown
Ready to get pre-approved with a local East Idaho lender?
📞 Call Valorie: (208) 403-1859Estimates are for informational purposes only and do not constitute a loan offer. Actual rates, taxes, and insurance vary by lender, county, and property. Consult a licensed lender for exact figures.
How to Use the East Idaho Mortgage Calculator
The calculator updates as you type, so you can test different scenarios in seconds. Below, you'll find what each field means and how to fill it in.
Not sure where to start? Right now, the median list price across East Idaho is $384,500, based on live Snake River MLS listings.
- Home price. Enter the list price of a home you like, or your target budget. Then drag the slider to compare price points quickly.
- Down payment. Slide to the percentage you plan to put down. The dollar amount updates right below it.
- Loan term. Choose 30, 20, 15, or 10 years. A shorter term raises the monthly payment, but you pay far less interest overall.
- Interest rate. Set the rate a lender quoted you. If you don't have a quote yet, try a range to see how much each quarter point matters.
- Property tax rate. Enter the yearly tax as a percentage of the price. The property tax section below explains what to use.
- Insurance and HOA. Add your yearly homeowners insurance estimate and any monthly HOA dues. Many rural and acreage homes have no HOA at all.
What Goes Into Your Monthly Mortgage Payment
Lenders often call your full payment PITI, short for principal, interest, taxes, and insurance. In addition, some buyers pay mortgage insurance or HOA dues. Here's how each piece works.
Principal and interest
Principal pays down your loan balance, while interest is the cost of borrowing. Early in a 30-year loan, most of each payment goes to interest. Over time, more of it goes to principal.
Property taxes
Your county bills property taxes each year. Most lenders, however, collect a monthly share through an escrow account and pay the bill for you.
Homeowners insurance
Lenders require coverage for the home itself. On top of that, rural homes can cost more to insure. Barns, shops, and other outbuildings may need extra coverage, so get an insurance quote early.
PMI
Conventional loans with less than 20% down usually carry private mortgage insurance. Under federal law, you can ask to cancel it once your balance reaches 80% of the home's original value. After that, it ends automatically at 78%.
HOA fees
Some subdivisions charge dues for shared roads, common areas, or amenities. Check each listing's MLS details for the amount and whether it's billed monthly or yearly.
Closing costs
Because closing costs are paid once, they don't appear in your monthly total. Still, plan for them in your cash to close, along with your down payment.
East Idaho Property Taxes: What to Enter
Idaho's effective property tax rate is among the lowest in the country. Even so, your actual bill depends on local levies for schools, cities, counties, and fire districts. As a result, two similar homes a few miles apart can pay different amounts.
The calculator starts at 0.8%, which is a cautious estimate. For a closer number, open the listing's MLS details and divide the yearly tax by the price. Keep in mind that the current owner's exemptions won't carry over to you.
Apply for the homeowner's exemption
If the home will be your primary residence, apply for the homeowner's exemption with your county assessor. It exempts 50% of your home's value and up to one acre of land. The maximum exemption is $125,000. Learn more on the Idaho State Tax Commission's homeowner's exemption page.
When property taxes are due
Counties bill property taxes in two halves. The first half is due December 20, and the second half is due June 20. If your lender escrows your taxes, it pays both halves for you.
Local tax levies and market trends vary by county. For a closer look, compare the Bonneville County, Madison County, and Jefferson County guides.
Financing Horse Property and Acreage in East Idaho
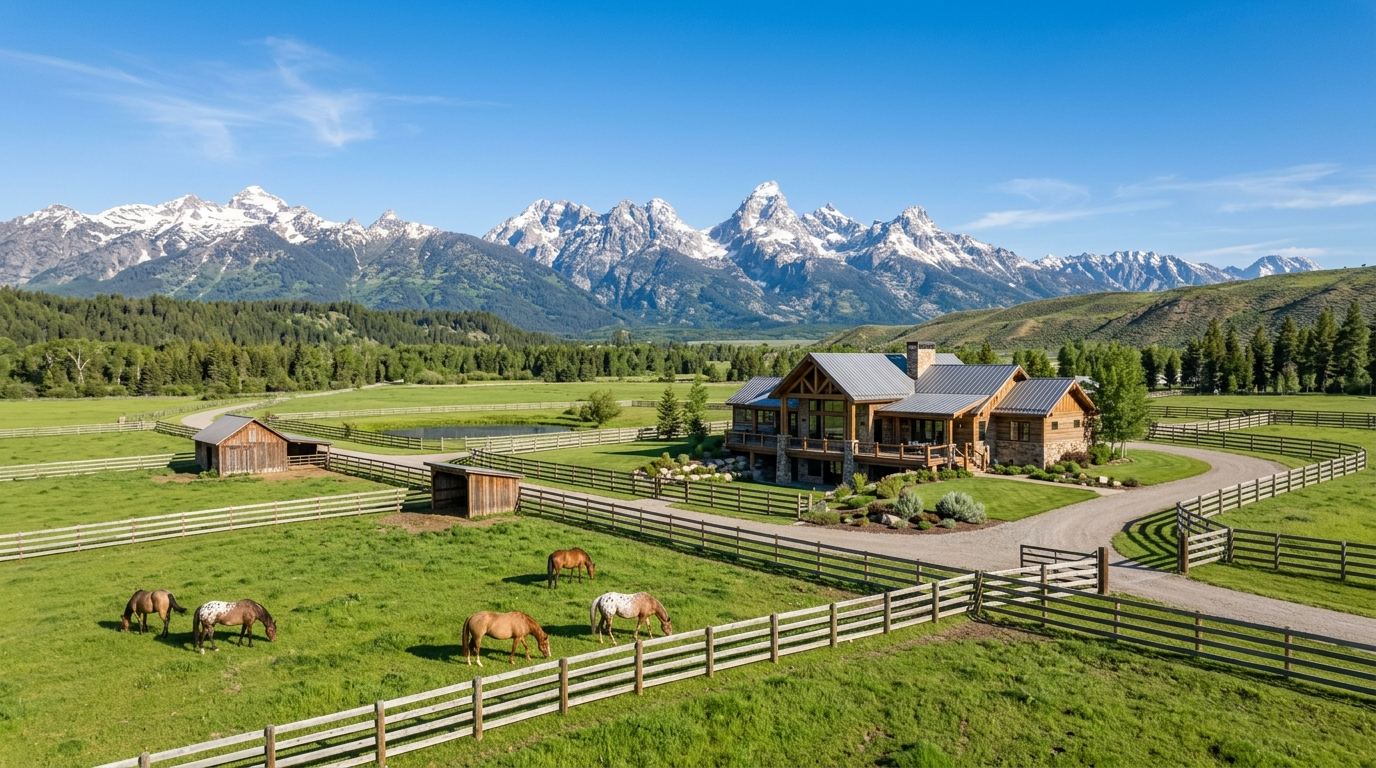
Acreage, pasture, and horse property make up a big part of the East Idaho market. However, lenders often look at these homes differently than a house in town.
- Land value matters. If land makes up a large share of the value, some lenders ask for more money down.
- Outbuildings get a closer look. Barns, shops, and arenas can add value. Still, appraisers may give them less credit than you expect.
- Wells, septic, and water. Budget for well, septic, and water quality inspections. Also ask whether canal or irrigation assessments come with the parcel.
- Working farms and ranches. Larger agricultural properties may fit a farm and ranch lender better than a standard home loan.
Valorie has 10+ years of experience helping buyers weigh water rights, pasture, and outbuildings. Browse current East Idaho horse properties, then run the numbers here.
Loan Options to Compare in the East Idaho Mortgage Calculator
Each loan type changes your down payment, mortgage insurance, and monthly cost. So, try each scenario in the calculator and compare the results.
Conventional loans
Some programs allow as little as 3% down, with PMI until you reach 20% equity. For 2026, the baseline conforming loan limit for a one-unit home is $832,750.
FHA loans
FHA loans allow 3.5% down for qualifying buyers. They carry mortgage insurance, which often lasts for the life of the loan when you put down less than 10%.
VA loans
Eligible veterans and service members can often buy with no down payment and no monthly mortgage insurance. A one-time funding fee usually applies unless you're exempt.
USDA loans
Some homes in smaller towns and rural areas qualify for USDA loans with zero down for income-eligible buyers. Check a specific address on the USDA eligibility map.
Down payment help from Idaho Housing
The Idaho Housing and Finance Association offers down payment and closing cost assistance through approved local lenders. Today, that help is a repayable second mortgage rather than a grant. Also, you don't have to be a first-time buyer to apply.
Five Ways to Lower Your Monthly Payment
- Compare lender quotes. Even a small rate difference adds up over 30 years. Try it now: change the rate by a quarter point and watch the payment move.
- Aim for 20% down. On a conventional loan, this removes PMI from your payment entirely.
- File your homeowner's exemption. It can cut the taxable value of a primary residence by up to $125,000.
- Shop your insurance. Rates vary widely, especially for rural homes with outbuildings.
- Negotiate beyond price. Ask about seller-paid closing costs or a rate buydown. These credits can lower your cash to close or your monthly payment.
East Idaho Mortgage Calculator FAQs
How accurate is this East Idaho mortgage calculator?
It gives you a solid planning estimate, not a loan quote. Your final payment depends on your credit, rate, lender fees, taxes, and insurance. A pre-approval from a lender gives you exact figures.
What property tax rate should I use for an East Idaho home?
Start with the 0.8% default for a cautious estimate. Next, check the tax amount in the listing's MLS details. If the home will be your primary residence, the homeowner's exemption can lower your bill further.
How much do I need for a down payment in East Idaho?
It depends on the loan. For example, VA and USDA loans may allow zero down for eligible buyers. FHA loans start at 3.5%, and some conventional loans allow 3%. With 20% down on a conventional loan, you avoid PMI.
Does the calculator include PMI?
Yes. The payment breakdown includes an estimated PMI line. However, your lender will quote the real premium based on your credit score, down payment, and loan type.
Can I use the calculator for horse property or acreage?
Yes, it works well for a starting estimate. Keep in mind that land value, wells, septic systems, and outbuildings can affect your loan options, insurance, and taxes. For that reason, talk with a lender who regularly finances rural East Idaho homes.
Should I get pre-approved before I start shopping?
Yes. A pre-approval confirms the price range you can afford and shows sellers you are ready to act. Valorie can connect you with local lenders who know the East Idaho market.
Ready to Put Your Numbers to Work?
Once you know your comfortable payment, you can shop with confidence. Browse homes in your price range, read the buyer guide, or call Valorie to talk through your plan.